Helen arranged for a digital records specialist to examine the old computer in my study. I signed the necessary consent forms and handed over the machine, along with a written description of when Benjamin had used it and which accounts might have been accessible.
The specialist explained that the examination would focus on records relevant to the disputed transactions. He would not assume that every saved document was connected to the investigation, and he would preserve the original data as far as possible.
I was grateful for the care he took. I did not want suspicion to become an excuse for treating every action Benjamin had ever taken as evidence of wrongdoing.
The examination took several days.
During that time, I continued reviewing my bank statements and responding to Helen's requests. I learned to distinguish between the payments I had knowingly made and the transactions that required further explanation. I also began keeping a written record of every conversation related to the disputed financing.
It was tedious work, but it gave me a sense of control I had not felt since receiving Benjamin's message about the dinner.
On the fourth day, Helen called.
“The specialist has found several relevant files,” she said. “Some appear to be copies of financial documents, and others are email drafts. We need to review them carefully before drawing conclusions.”
“Do they show who initiated the payments?”
“Not conclusively yet. But there is a draft message addressed to the legal services firm that may help establish how the financial summary was prepared.”
I sat down.
“Was it written by Benjamin?”
“The file's metadata identifies the account used to create it, but metadata alone does not establish who was operating the computer. The content is more important than the name attached to the file.”
Helen sent me a copy of the draft through her secure document system. I opened it only after confirming that it was the version she wanted me to review.
The message contained a list of my assets and an explanation of the support I had been providing to Benjamin's household. It referred to my home as a potential source of financial security and suggested that the lender could proceed on the assumption that family support would be available.
The draft did not contain a direct instruction to forge my signature. It did, however, describe my willingness to help in a way that went beyond anything I had actually agreed to.
I read it twice, then closed the file.
For years, I had believed that Benjamin's financial requests were separate emergencies. Now I could see that someone had been assembling the pieces into a larger picture: my assets, my income, my previous payments, and the property that might be used to support additional financing.
I called Helen.
“I want the bank and lender to receive the complete context,” I said. “I don't want a single sentence taken out of these records to suggest that I agreed to something I never approved.”
“We will make sure your formal position is clear,” she replied. “The original records will be preserved, and any response will distinguish between what the documents establish and what remains uncertain.”
That afternoon, I received a call from Benjamin.
He sounded unusually calm.
“Mom, Helen says you've seen some of the computer records.”
“I have seen the documents she sent me.”
“I want to explain them.”
“Then explain them to Helen.”
“I need you to hear it from me.”
I closed my eyes briefly.
“All right. Tell me what you want me to understand.”
He said that when he had visited me to help with the insurance paperwork, he had found several financial documents in the study. He had copied them because he wanted to understand whether I could help with the company's refinancing. He claimed that he had not intended to use the information without my permission and had believed I would eventually agree to provide support.
“Did I tell you that I would guarantee the financing?” I asked.
“No.”
“Did I tell you that you could share my financial information with a legal firm?”
“No.”
“Then what gave you the right to do it?”
He was silent.
“I thought you would help once you understood how bad things were,” he finally said.
“You had years to explain how bad things were.”
“I was ashamed.”
“I understand shame, Benjamin. But shame does not give you permission to make decisions for someone else.”
His breathing became uneven.
“I know I hurt you.”
“Yes.”
“I don't know how to make this right.”
I looked out at the maple tree, whose branches had begun to thin.
“Start by telling Helen the complete truth. Don't leave out details because you think they will make you look worse. And don't ask me to promise what I will do before the investigation is finished.”
He agreed, though his voice sounded defeated.
After the call, I remained at the table for a long time. I was beginning to understand that Benjamin's central mistake had not been a single forged signature or a single unauthorized payment. It was the belief that my love could be treated as a resource he could draw upon whenever he needed it, even when I had not agreed to the terms.
That belief had developed gradually. Each time I covered an unexpected expense without asking questions, he learned that a difficult conversation could be postponed. Each time I accepted an apology without requiring a change in behavior, he learned that remorse could substitute for accountability.
I did not blame myself for his choices. But I could no longer ignore the ways my own habits had allowed the pattern to continue.
Two days later, Helen invited me to her office to review the specialist's findings. The computer contained a draft email to the legal services firm, copies of the financial summary, and a spreadsheet listing payments made toward Benjamin's household and business expenses.
The spreadsheet was especially troubling.
It included amounts I recognized from my bank statements, but it also contained estimates of future support. Some entries referred to expected monthly contributions from me, as though the money had already been promised.
I pointed to one line.
“This says I would cover the next six months of mortgage payments.”
Helen examined the entry.
“Did you ever agree to that?”
“No.”
“Then we will record it as a projected payment that you did not authorize.”
The spreadsheet also contained a column labeled FAMILY SUPPORT. Several entries were marked as confirmed, although I had never been asked to confirm them.
I felt a hollow ache in my chest.
My son had taken the uncertainty of my generosity and turned it into a financial assumption. Other people had been shown a plan that treated my future decisions as though they were already settled.
“Did Genevieve prepare this?” I asked.
“The file does not establish who entered every figure. We have asked for additional records from the holding company and the legal firm.”
I nodded.
I wanted a name, a clear answer, and a reason that would make the past easier to understand. But the investigation was forcing me to accept that some questions could not be answered simply because I needed them to be.
Helen showed me another file: a draft letter intended for the lender. It described me as a supportive family member who understood the proposed arrangement and was expected to assist with the financing.
There was no direct statement that I had signed the authorization, but the wording could easily lead a reader to believe I had approved the plan.
“Who wrote this?” I asked.
“The file was saved under the holding company's account. We cannot yet establish who drafted the language.”
I studied the document.
It was not the same as the disputed authorization, but it served a similar purpose. It portrayed my support as dependable, my consent as likely, and my assets as available.
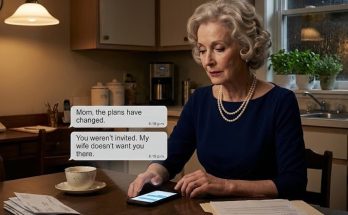
I thought of the night Benjamin told me I was not invited to dinner because Genevieve did not want me there. I had wondered whether they were ashamed of my age, my clothes, or the questions I might ask.
Now I understood that they had also been afraid I might speak honestly about the money.
They needed me to remain generous, but they did not want me present when their guests might ask how they had paid for their lifestyle.
That afternoon, Helen received confirmation that the bank had placed a formal restriction on changes to the disputed account arrangements while the review continued. It was a protective measure, not a final judgment about what had happened. The lender had also acknowledged that my consent remained disputed.
For the first time, I felt that the process was moving toward a clear examination of the facts rather than an endless exchange of excuses.
Then Helen asked me a question I had not expected.
“Margaret, did Benjamin ever ask you to sign a document connected to the townhouse purchase?”
I thought back over the previous year.
“He showed me a few papers about the property investment, but I don't remember signing anything. I would have kept a copy if I had signed a financial agreement.”
“Did he ever ask you to sign a blank form or a document that had not been completed?”
“No.”
“Did you ever give him permission to sign your name on your behalf?”
“Never.”
Helen recorded my answers.
She then showed me a message from the legal services firm. It confirmed that the firm had received instructions to prepare documents connected to the proposed transaction, but it had not received a signed engagement letter from me. The firm was reviewing its records to determine who had instructed it and what it had been told about my role.
The distinction mattered. I had not hired the firm, and I had not knowingly asked it to prepare a property transaction involving my home.
I left Helen's office feeling exhausted but more certain of the boundaries I needed to maintain.
At home, I found a letter from the bank requesting that I confirm several details about my accounts. I completed it carefully, attaching copies of the disputed documents and confirming that I had not authorized the financing.
Then I placed the letter in an envelope addressed to the bank's legal department.
For years, I had signed forms without thinking twice when Benjamin assured me they were routine. Now I read every line, checked every attachment, and kept copies of everything I sent.
The next morning, Patricia called to tell me that Genevieve had asked her to help find a way to settle the dispute privately.
“What did you tell her?” I asked.
“I told her that she needed to speak to her own lawyer and provide the complete records.”
“Did she explain what kind of settlement she wanted?”
“She wanted to know whether you might agree to continue helping with the mortgage while they sorted out the company debts.”
I closed my eyes.
Even now, with the authorization disputed and the transaction paused, the first solution they had considered was another payment from me.
“Patricia, I cannot make a financial promise to keep their situation comfortable while the investigation is underway.”
“I told her that.”
“Thank you.”
After we ended the call, I sat quietly at the kitchen table. I was no longer surprised by the request, but the familiarity of it still hurt. The townhouse remained the center of their fears, and my money remained the first resource they reached for whenever those fears became unbearable.
That evening, I received an email from Benjamin containing a signed statement. He admitted that he had copied my signature from an older document and used it in preparing the disputed financial authorization. He said he had acted under pressure and had expected to obtain my approval before the transaction became final.
I forwarded the statement to Helen.
It was an important admission, but it did not answer every question. It did not establish who else knew what he had done, who had requested the property valuation, or why the legal firm had been paid from my accounts.
Still, for the first time, Benjamin had put part of the truth in writing without claiming that I had somehow agreed to it.
I sat beside Thomas's photograph and read the statement once more.
I loved my son. I wanted him to find a way forward that did not destroy his future. But I could no longer confuse wanting him to recover with being responsible for rescuing him.
The next morning, Helen called.
“The holding company has provided a new set of records,” she said. “One document concerns the ownership of the townhouse, and another concerns the proposed sale to you. There is a clause in the ownership agreement that may affect what happens next.”
I gripped the phone.
“What kind of clause?”
“It concerns the transfer of Benjamin's interest to Genevieve and the company's authority to sell the property. We need to review the original agreement before drawing a conclusion.”
I looked toward the folder on my desk.
For weeks, I had believed that the townhouse was simply a house my son could lose if I stopped paying his bills. Now I was beginning to understand that its ownership and financing were more complicated than either of them had admitted.
And the clause Helen had found might determine whether Benjamin and Genevieve could decide the property's future at all.
Click here to continue reading: PART 12: The Townhouse Agreement Contained a Clause Neither Benjamin Nor Genevieve Had Expected Me to Discover
I Had Spent the Evening Preparing for My Son’s Dinner When Two Messages Revealed How Little My Place in His Life Meant
Part 11 of 20